Posted on — Leave a comment

Is Cash in the Bank High Risk? Bank Bail-In Laws

Gold finished strongly for the week. After early resistance near AUD $5,150, it pushed above $5,200, and currently trades at $5,189.  Silver, on the other hand, saw a more volatile $2 trading range before reaching higher and is at $59.53.  Platinum, at $2101, remained steady largely moving sideways. Precious metals continue to benefit from uncertainty in global financial systems, with one issue coming into sharper focus as we edge closer to a major correction: Australian bank bail-in laws. These laws, introduced in 2018, could directly impact those holding cash deposits, and highlight why gold, silver, and platinum remain critical stores of value outside of the banking system.  Passed by the Senate on Valentine’s Day, the laws are less of a love letter to Australian bank depositors and more like a tightly sealed pre-nuptial agreement that you probably never read before investing in the relationship.


Australia’s bail-in laws

In 2018, amendments to the Banking Act 1959 via the Financial Sector Legislation Amendment (Crisis Resolution Powers and Other Measures) Act brought Australia in line with the Bank for International Settlements’ (BIS) global “bail-in” framework, agreed at the 2014 Brisbane G20. Unlike the 2008 bail-outs that used taxpayer money to rescue failing banks, bail-ins place the burden on a bank’s creditors which, crucially, can include depositors.

Under the law, APRA (the Australian Prudential Regulation Authority) has “crisis powers” to step in, run distressed banks, and convert certain securities or deposits into capital to stabilise the institution. SMSF cash holdings are explicitly exposed, while ordinary deposit accounts are not excluded, which opens them to the possibility that they also could be written down or confiscated in a crisis. Rather than curbing risky investment behaviour by banks, the framework prioritises repayment of banks’ derivatives obligations ahead of depositors, raising concerns that everyday savers could be sacrificed to protect interbank exposures.

Bail-in versus bail-out

A bail-out involves taxpayer-funded capital injections, as seen during the Global Financial Crisis when governments rescued banks in the U.S. and Europe. Australia has historically avoided direct bail-outs, though during 2008–09 it guaranteed deposits and wholesale funding to protect stability. Bail-ins, by contrast, recapitalise failing banks by forcing creditors (including bondholders, hybrid investors, and potentially depositors) to absorb losses. This reduces taxpayer exposure but shifts risk squarely onto the private sector, potentially including those with cash in the banks.  By passing bail-in laws, Australia is just one of the G20 countries positioned to prioritise banks over people by legally being able to confiscate cash deposits in banks.


Who are the creditors that bail-in applies to?

In essence, when you deposit money into a bank account you lend that money to the bank.  This is why they pay you interest.  The banks then use your money to fund other projects, all of which allow them to produce a profit.  They do this under a fractional reserve system and retain only a small portion as liquid reserves.  You hold the right to demand payment which is what happens when you withdraw your money from the bank.  But until you withdraw it they loan it from you.  Because you lend your money to the bank, you hold the status of unsecured creditor.  And as a creditor, you could be subject to bail-in laws.  Under bail-in law, your right to claim payment can be written down if a bank is in distress, putting depositor funds at risk.


The $250,000 deposit guarantee is not absolute

People are generally more aware of Australia’s Financial Claims Scheme (FCS) than bail-in laws.  The FCS may provide a government guarantee of up to AUD $250,000 per account holder, per authorised deposit-taking institution (ADI).  Falling back on the FCS is often the first response from people on learning of the bail-in laws in an effort to dismiss risk.

However, this protection has limits:

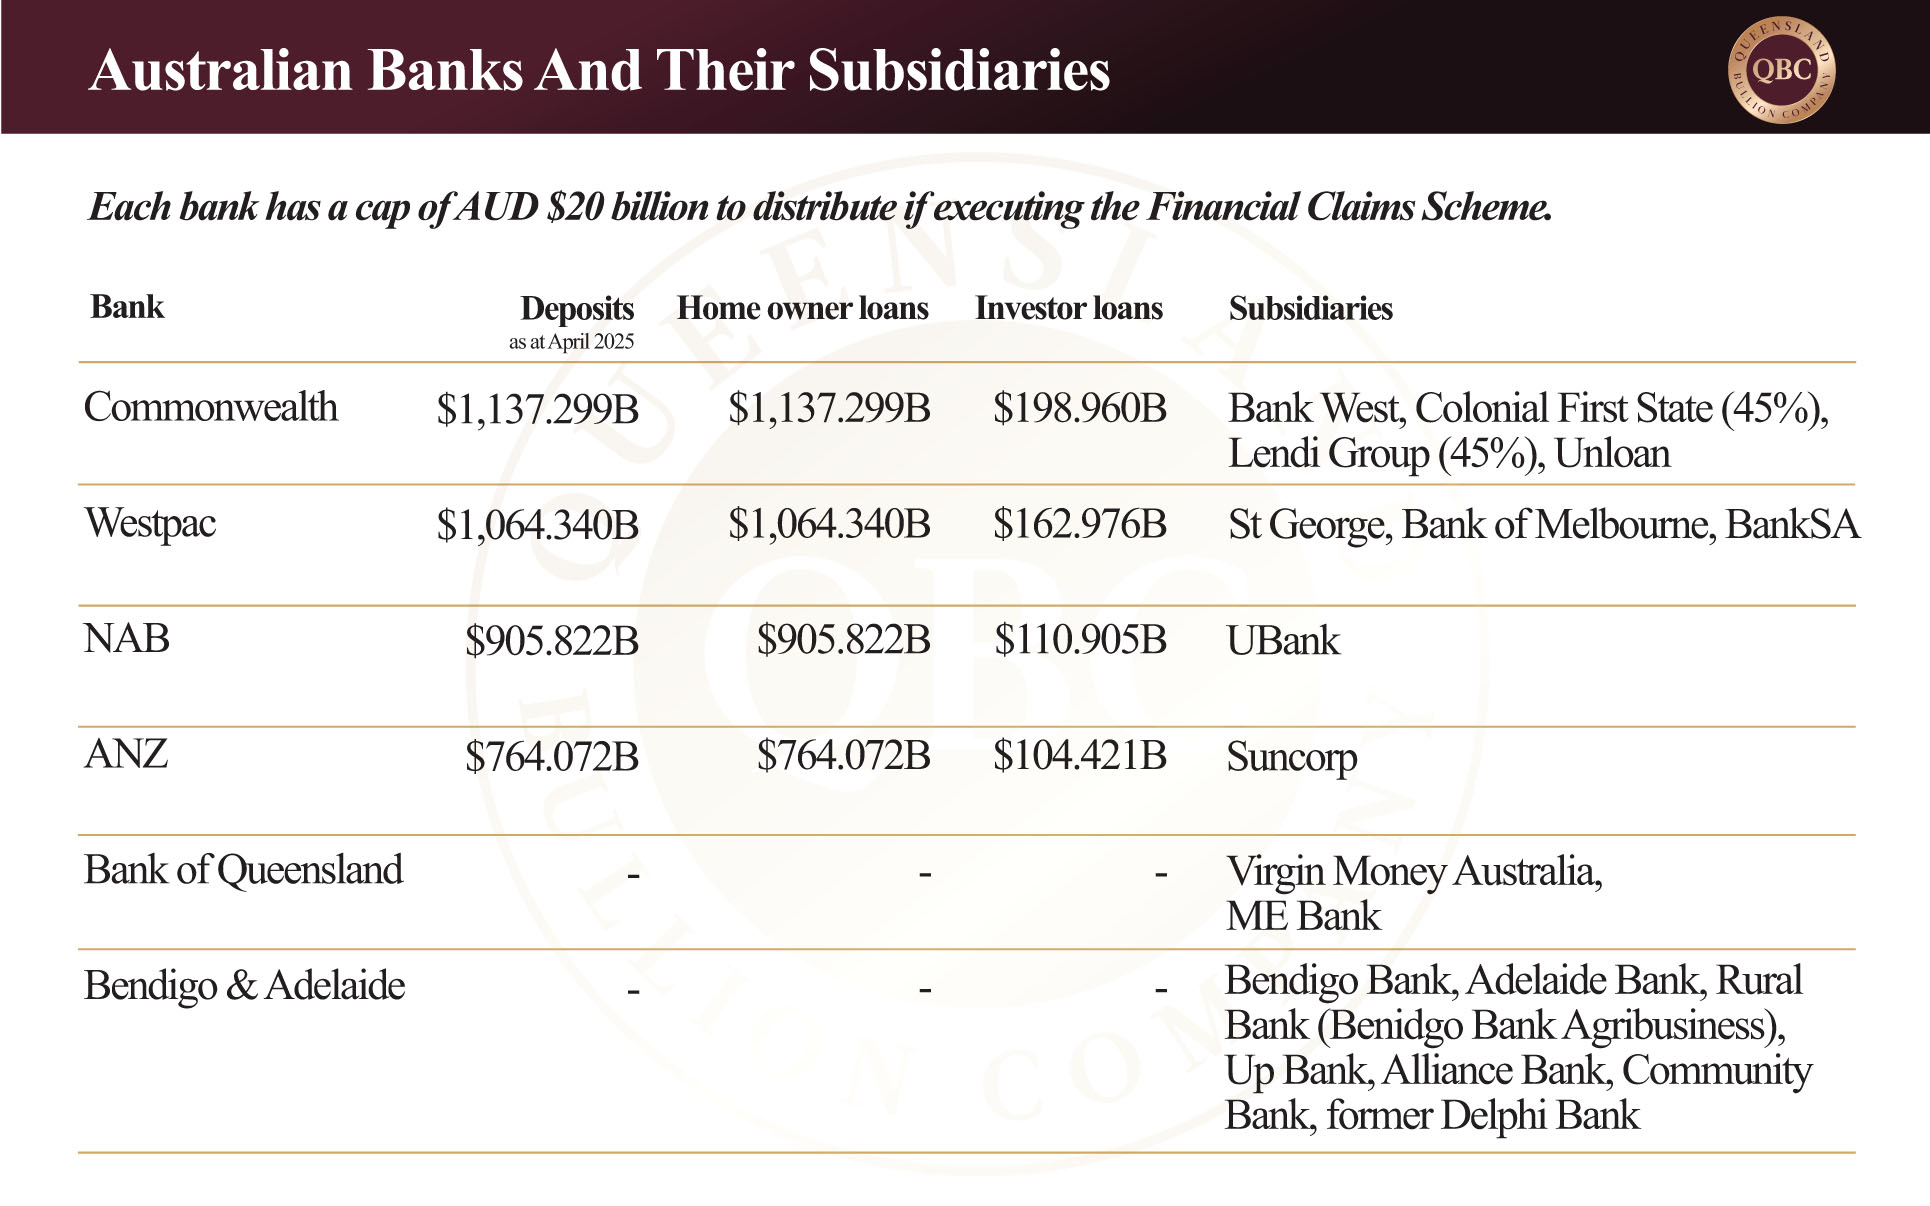
Multiple banks under a single licence are treated as one entity. This means that if a person’s wealth is spread across two entities that share a licence, the guarantee is split between them.  For example if an individual has $50,000 deposited with St George, another $200,000 with Bank of Melbourne, and $300,000 with Westpac, they are only guaranteed a total of $250,000 across all accounts because these banks all use the same licence.  They could lose at least $300,000 (if not more) should the FCS ever be activated to “protect” their financial assets.

The $20 billion cap per ADI may be insufficient for large institutions. Refer to the table below and consider how far this will stretch across each bank and their deposits, and subsidiaries.

Critically, bail-in powers are applied before the FCS is triggered, meaning depositor funds could be used to stabilise the bank first. And only if the bank fails outright would the FCS potentially provide reimbursement.

Due process guarantees a delayed payment. FCS are to be paid out “within seven days.”  However, this starts after APRA’s attempt to first rescue the failing institution (by implementing bail-in), then they must apply to the Treasurer for support to declare the institution insolvent.  This process must go through the courts, then FCS is implemented, and you get the remainder of your money after bail-in “within seven days.”


Why this matters for investors

The IMF has noted that bail-in laws indemnify bank executives from liability, further shielding institutions and reducing accountability. This framework makes clear that in a crisis, depositor protection is not absolute. Holding significant cash in banks exposes savers to the risk of their funds being used to rescue the very institutions meant to safeguard them.

With bail-in laws enshrined in Australia, cash in the bank is not risk-free. Depositors are legally creditors and their funds could be at risk should a bank faces distress. This reinforces the case for precious metals as a decentralised, tangible store of wealth that sits outside the banking system. Gold, silver, and platinum cannot be “bailed in,” written down, or subjected to derivative losses. At a time when global monetary policy and financial stability are under strain, bullion offers investors independence and protection that bank deposits simply cannot guarantee.  Those savvy with their wealth understand what Shakespeare meant when he penned “it is better to be three hours early than one minute late.”  Preparation with a layered defence before a financial correction allows time for unexpected delays, avoids panic, reduces stress, and provides stability and strategy for the investor and consequently their dependents.  There has never been a better reason to invest in gold and silver today.

Posted on — Leave a comment

Simple Digital Gold Purchasing: From Smartphone to Secure Vault

buy gold online simply

Investing in Precious Metals Made Easy

In today’s fast-paced digital world, investing in precious metals has never been more straightforward. Gone are the days of visiting multiple bullion dealers, negotiating prices, or worrying about authenticity. With modern technology, you can now buy gold online directly from your smartphone and have it securely stored in a professional vault. This evolution in bullion trading combines convenience, transparency, and security, making it easier than ever to grow or diversify your portfolio with gold, silver, and platinum.

The Modern Bullion Buying Experience

Traditionally, purchasing physical silver or gold involved time-consuming visits to stores, limited product selection, and concerns over pricing accuracy. Digital platforms have changed this completely. Much like online banking, stock trading, or cryptocurrency platforms, investors can now browse, compare, and buy and sell bullion online in real time. Prices are updated instantly, based on current spot prices for gold, silver, and platinum, ensuring investors always transact at market-accurate values rather than outdated figures.

Security Without Compromise

A key concern when buying bullion online is security, both in the transaction itself and in the delivery or safekeeping of your investment. At Queensland Bullion Company, we provide multiple layers of protection. Secure payment gateways safeguard your financial details, while professional vault storage ensures your gold, silver, or platinum is protected with full replacement-value insurance. We also offer multiple storage options: premium segregated storage for individual bars and coins, secure collective holdings, and pooled allocated storage for cost efficiency. Each option is fully insured, giving you peace of mind that your bullion is safe against theft, damage, or loss.

Trading Pool Allocated Gold, Silver, and Platinum

One of the most cost-effective and convenient ways to trade precious metals is through our pool allocated bullion program. This service allows investors to purchase fractional ownership of larger bars according to budget or weight, making it simple to sell or buy gold, silver, and platinum online. With instant transactions and payments cleared within one business day, pool allocation offers seamless trading with full insurance and the confidence that your holdings are backed by physical bullion in our vault. If desired, pool allocations can easily be converted into physical bars or coins, with no appointment necessary.

A Streamlined Investment Process

Whether you prefer physical coins and bars or pooled allocations, the process of acquiring bullion is fast and efficient. Our platform provides transparent pricing, detailed product information, and high-resolution images to support informed decision-making. Investors can choose insured delivery Australia-wide or secure vault storage. From a single coin to a larger bullion portfolio, Queensland Bullion Company ensures every step, from browsing to settlement, is handled with precision and professionalism.

The Future of Precious Metals Investment

Digital gold purchasing is the natural evolution of bullion investment. At Queensland Bullion Company, we combine the timeless value of owning physical precious metals with the modern convenience of buying and selling bullion online. For Australian investors, this approach provides an efficient, secure, and cost-effective way to access the gold, silver, and platinum markets. By offering the flexibility of digital trading with the reassurance of physical storage, we put control firmly in your hands while maintaining the security and trust that only tangible assets can provide.

Posted on — Leave a comment

Where the World’s Wealth Really Sits And Why the Skew Matters

Precious metals like gold, silver, and platinum have served as anchors of value for centuries, yet today they occupy only a fraction of global wealth. Spot prices currently stand at AUD $5,145 for gold $58.76 for silver, and $2,098 for platinum — levels that, when viewed against other asset classes, suggest precious metals have a long way to go despite enjoying record pricing. Meanwhile, vast sums are concentrated in asset classes where valuations are flashing warning signs.


Real Estate – The Global Asset Juggernaut

Real estate remains the preeminent asset class worldwide, often seen as an essential first goal for most retail investors. The industry totals at an estimated $300–400 trillion. This includes everything from owner-occupied homes and farmlands to multi-billion-dollar commercial developments. Although real estate is traditionally viewed as a stable, inflation-protected asset, there are emerging vulnerabilities. Post-pandemic, office spaces face structural demand shifts, and financing costs are tightening as central banks recalibrate interest rates. Demographic shifts and a mixed outlook for commercial use further cloud the picture. Added to this, the 18.6 year economic and real estate cycle suggests there could be up to another twelve months of high times for estate agents as they squeeze the last commissions out prior to the expected correction.  As a case in point, Sydney now “stands alone” as the most expensive city in the world for housing.  Extrapolate this around the country and it suggests the real estate bubble in Australia could be the largest elephant in the room.


Bonds – A System Under Strain

The global bond market remains the second largest financial asset class, valued at $130–150 trillion, encompassing government, corporate, and municipal debt. What’s particularly striking is how the debt ceiling has evolved from a legal limit into a baseline expectation for perpetual government spending. With central banks expanding their balance sheets and inflation proving sticky, policymakers appear trapped, facing a lose-lose between maintaining credibility and ensuring solvency. These are problems that cannot simply be printed away and this, in turn, chips away at confidence in fiat currency systems.

In this context, traditional safe-haven assets like U.S. Treasuries lose their appeal as yields drop. In comparison, physical gold and silver (non-counterparty, tangible, and historically resilient) emerge as rare stores of value that are not subject to the same fiscal pressures.  And despite not offering regular yields, they don’t rely on sovereign promises and are immune to default or devaluation risk, reinforcing their role as essential portfolio hedges.  As central bank interest rate cutting cycles ramp up look to see if there is a transfer of capital away from bonds and into precious metals.


The Equity Bubble – $100–120 Trillion

The global stock market, valued at USD $100 to 120 trillion, is not just large — it is historically expensive. A Bank of America survey indicates 91% of global fund managers believe U.S. stocks are overvalued, the highest since 2001, reflecting widespread concern about a potential bubble.  The Buffett Indicator (total stock market capitalisation divided by GDP) is now above 170% globally and over 210% in the U.S., far beyond the long-term average of approximately 100%. This signals a market priced for perfection to take profits but also highly vulnerable to economic shocks.

U.S. equities dominate with USD $50 to 60 trillion in value, and a staggering 55% of that is now tied to technology and tech-related companies. The “Magnificent Seven” alone account for 34% of the S&P 500’s total market capitalisation, up from 12% just a decade ago. Such concentration not only inflates valuations but also magnifies systemic risk; if one sector falters, the ripple effect could be severe.

While equities are celebrated for their growth potential, the current valuations imply minimal margin for error. For investors seeking safety, this is a time to question whether they are overpaying for future returns.


Precious Metals – The Overlooked Hedge

Despite their enduring role as stores of value, gold and silver account for just 2 to 3% of global financial assets (approximately USD $12 to15 trillion), with physical bullion holdings representing a tiny 0.1%. Retail investors typically allocate about 1% of their portfolios to gold, with silver allocations even smaller; professional wealth managers often hold none at all.

This low allocation stands in stark contrast to expert recommendations of 10 to 20% in precious metals. The material reality is that financial advisors simply do not recommend physical metals to retail investors because there is no commission on offer.  And if an investor prioritises regular yields (as opposed to wealth preservation) then capital gains may not be appealing enough to recommend.

Historically, gold and silver have preserved purchasing power through recessions, inflationary spikes, and market collapses. With stocks trading at historically stretched valuations and sovereign debt at record highs, the opportunity cost of holding bullion has rarely been lower. For patient investors, precious metals may be one of the few undervalued, time-tested safe havens left.


The Bigger Picture

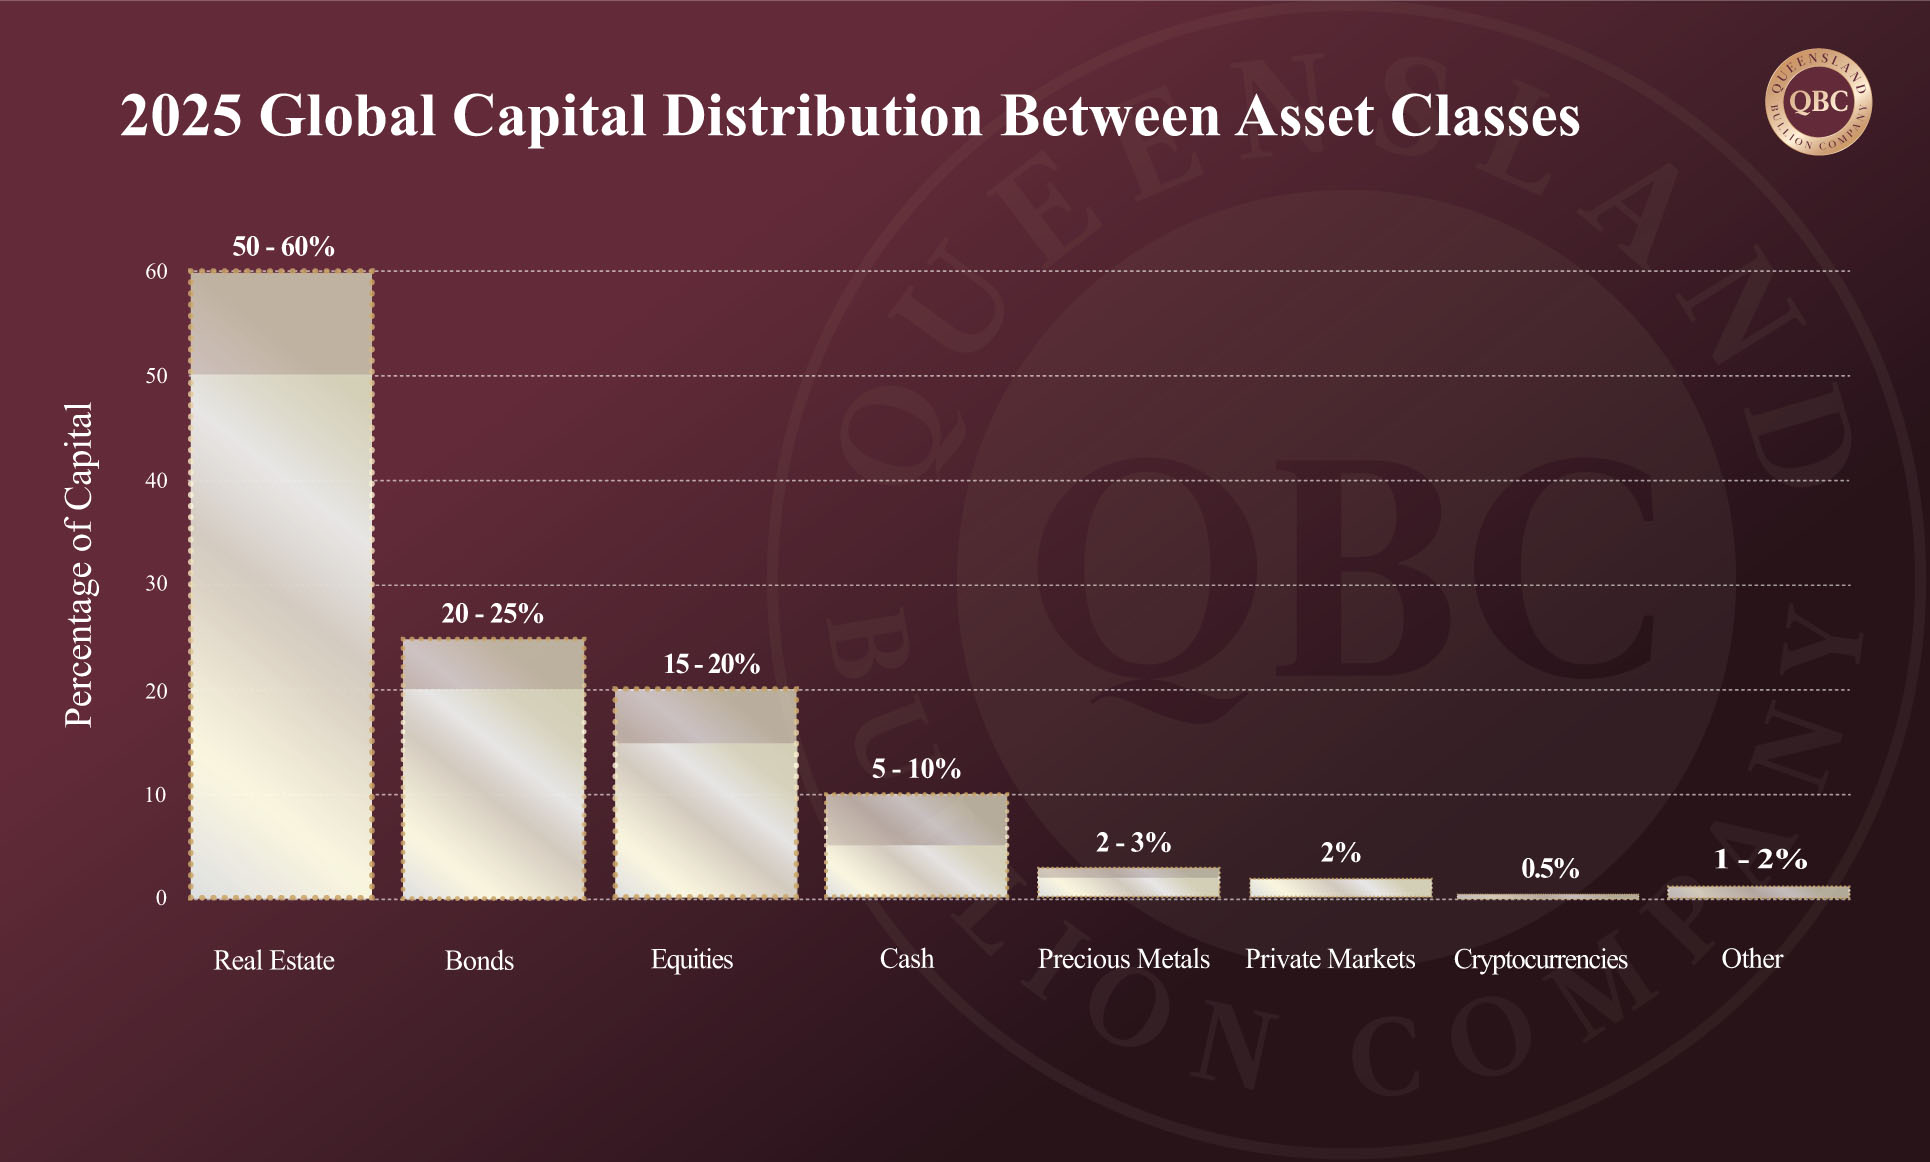
Currently capital is skewed towards risk-on assets.  Of the estimated $500 to 600 trillion in global financial assets, the vast majority is concentrated in real estate (50 to 60%), bonds (20 to 25%), and equities (15 to 20%). Precious metals occupy a fractional share, far smaller than cash, private markets, or even cryptocurrencies. Given the extreme valuations in stocks and the lowering yield prospects for bonds, this imbalance raises a simple question: when the tide turns, will capital flow back to the one asset class that has proven itself for over 5000 years?

Posted on — Leave a comment

Crisis Assets in Times of Chaos

Gold and silver have long been viewed a crisis hedge (assets that hold or gain value when markets turn volatile).  Over the last two decades, two major crises—the 2008 Global Financial Crisis (GFC) and the 2020 COVID crash—have tested this thesis.  Gold currently trades at $5,210, silver at $58.81, and platinum at $2,092.  All have offered significant gains to investors year to date.  Today, as global markets show signs of slowing and gold enjoys support above $5,100 in Australian dollars, it’s worth examining how these metals performed during those past upheavals and what the current technical landscape reveals about their evolving role in investor portfolios.


Gold crisis case study one: the GFC, a golden opportunity

During the Global Financial Crisis (GFC) gold proved its mettle. As with all asset classes it experienced a brief correction of 11.5% in late 2008 as liquidity evaporated and investors sold off assets indiscriminately to protect their wealth.  This sell off is typical of all major corrections and occurs in almost all asset classes, a knee-jerk reaction triggered by market panic. The only difference is that some asset classes bounce back faster than others.  Gold rebounded quickly and by 2011 (just over two years later) it reached a then-record high of AUD $1,714 (or an 85% increase), driven in Australia mainly by central bank easing, near zero interest rates, and ballooning sovereign debt.

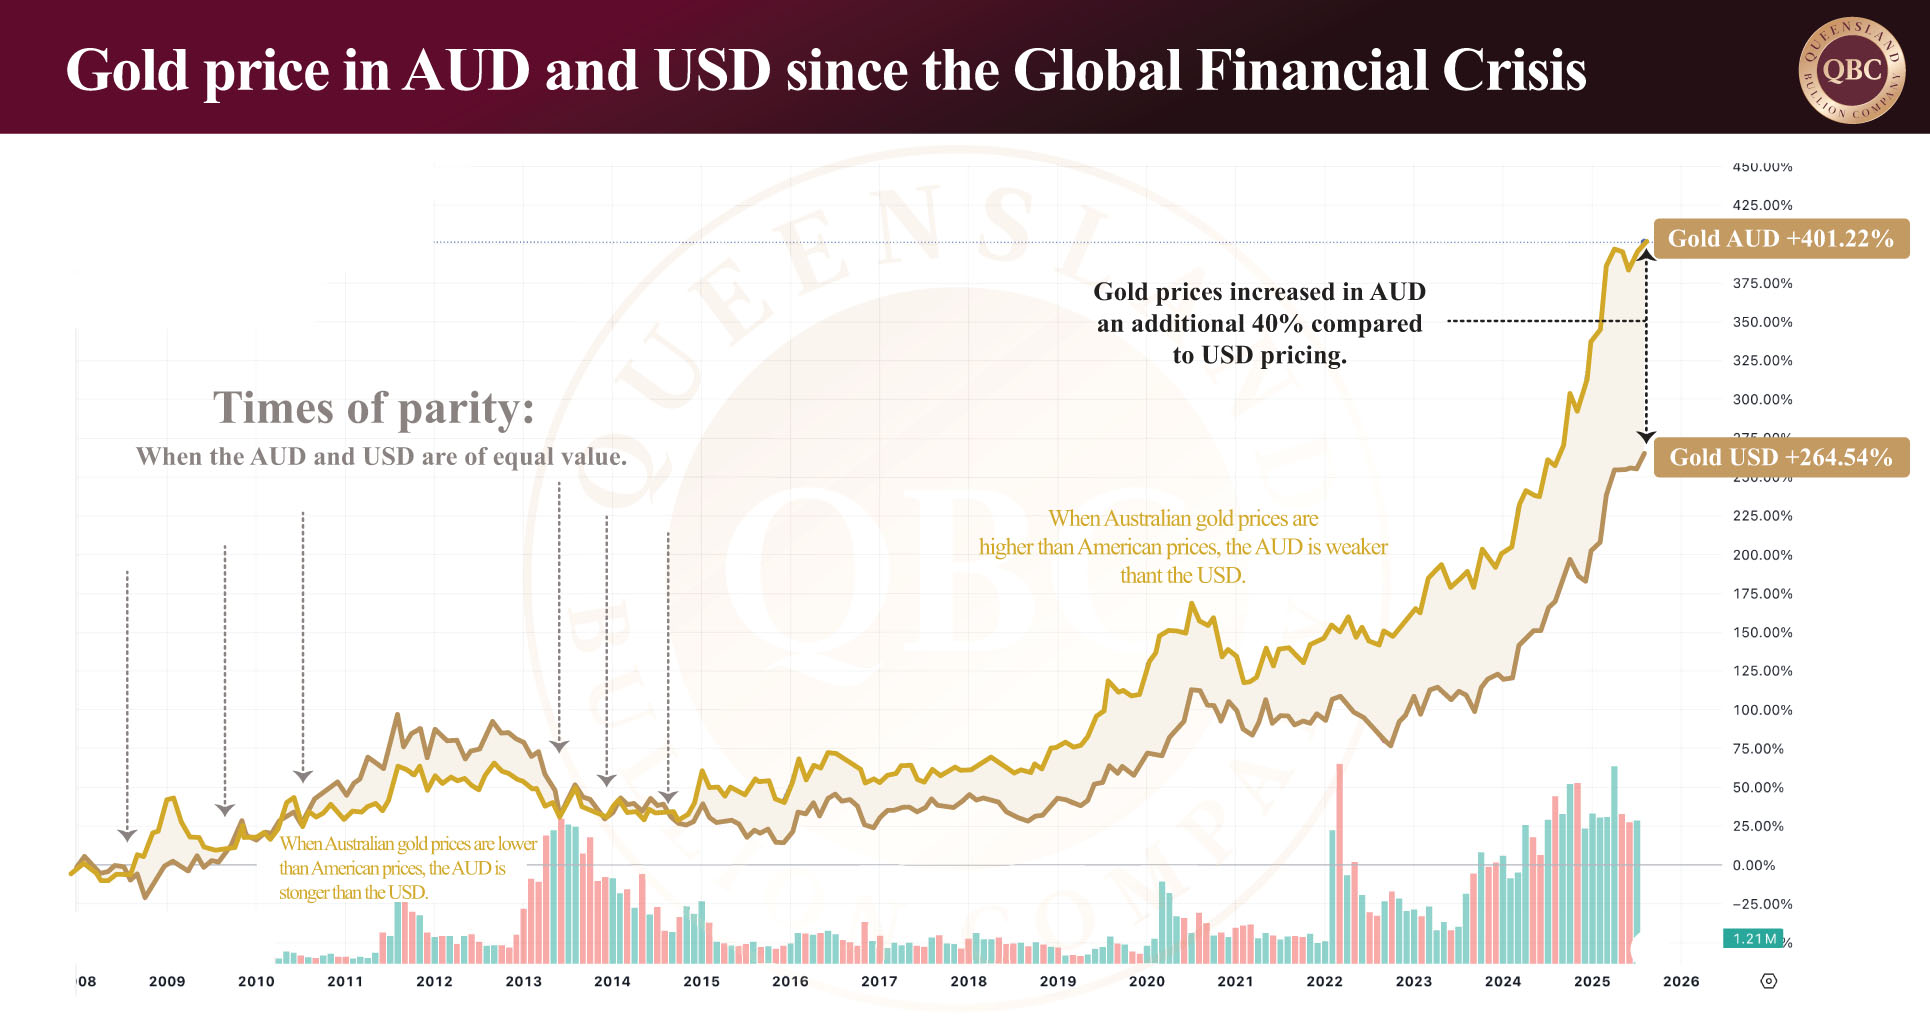
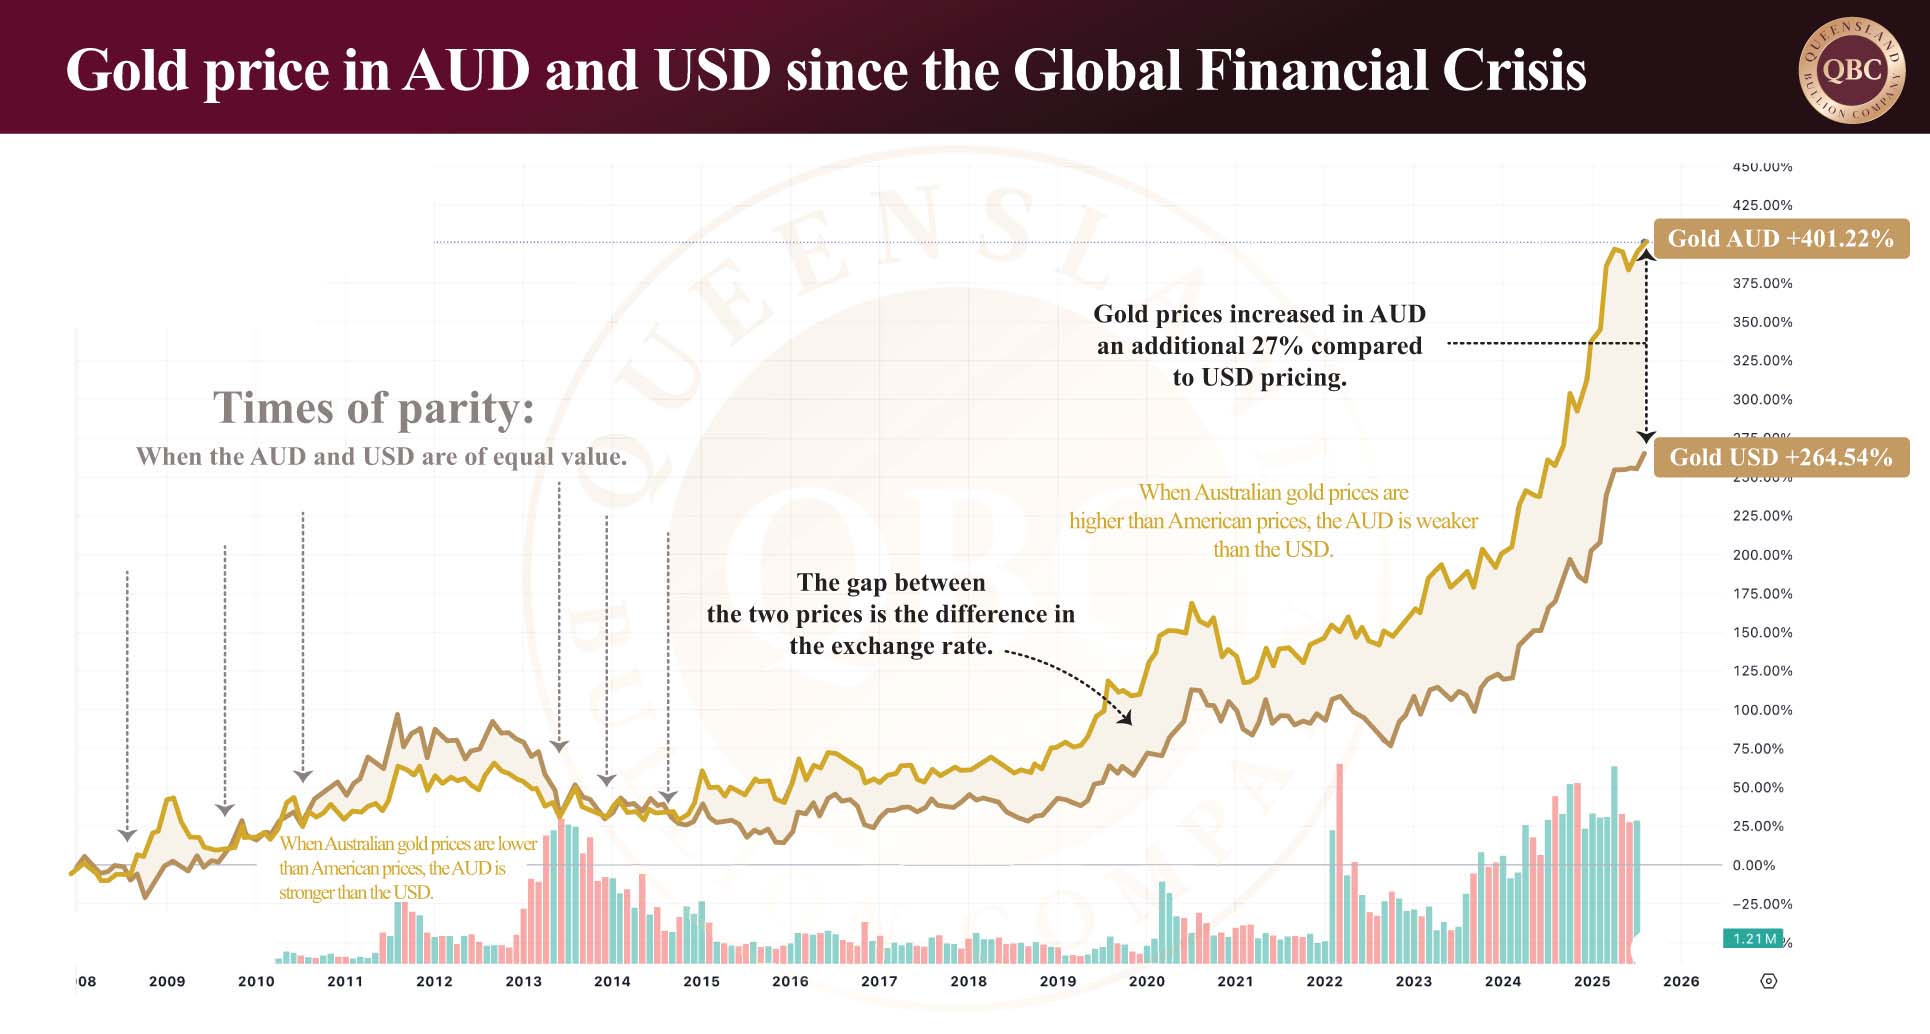
The increase was amplified by a weakening AUD, offering domestic investors exceptional returns; however, note how currency exchange is the one variable that affects local precious metal prices beyond the spot price which is in USD.  The graph below illustrates the difference in gold prices in AUD versus USD.  Since the GFC, gold increased an additional 27% in local markets compared to the American market to date.  This is due to the Australian dollar weakening against the Greenback over the same period.  In fact, the difference in the two prices directly reflects the variation in the exchange rate between the two currencies.

For example, if gold was to remain steady in USD and the Australian dollar weakens against the U.S. dollar, more local currency is needed to purchase the same amount of metal. Hence it increases in Australian dollars.


Gold crisis case study two: the Covid 19 Pandemic Era, the shock and the surge

The COVID financial crash of March 2020 initially hit all asset classes, including gold and silver. But by mid-year, gold had broken through AUD $2,700 for the first time, with the gold price in American dollars also reaching unprecedented highs. Massive global stimulus, near-zero interest rates, and fears of long-term inflation turbocharged the move.  This time gold initially increased as the stock market crashed, providing protection for those investing in safe haven assets; however, it did eventually correct as the pandemic unfolded and then travelled sideways until the end of 2022 when it started its current climb to new heights.

So why was this time different?  Simply put, markets were unable to play out the expected way due to government interference. The purpose of the interference was to maintain confidence in the economy and it worked: Australia avoided a formal recession that many parts of the world endured.  In this time the government gave away free money through a raft of measures such as Job Keeper payments, Job Seeker supplements, cash flow boosts for businesses, early access to Superannuation, cash payments to households, home-builder grants, loan guarantees and more.  Similarly, the Reserve Bank of Australia engaged in quantitative easing measures such as bond buy backs, cheap funding for banks, and record low rates.

While every government aims to avoid recession, the cost shows on the RBA’s balance sheet.  From AUD $180 billion, it ballooned to $640 billion at the height of the pandemic by early 2022.  It is a similar story in the U.S.  To learn more about the Federal Reserve’s predicament read our article, The Fed is Boxed In While Gold and Silver Look Ready to Fly.  While quantitative easing was employed after the GFC, the significance of its use during Covid is its cumulative effects.  Neither balance sheets for the RBA or the Fed are as healthy as pre-GFC and the Covid 19 Pandemic Era conditions.  It has been exacerbated despite attempts to curb the debt. The problem with holding too much debt is that eventually markets will lose confidence in the RBA or the Feds ability to honour their debt obligations which leads to a precarious financial position that could end in an almighty shakedown in various sectors of the economy.


Precious metals in 2025: consolidation or take off?

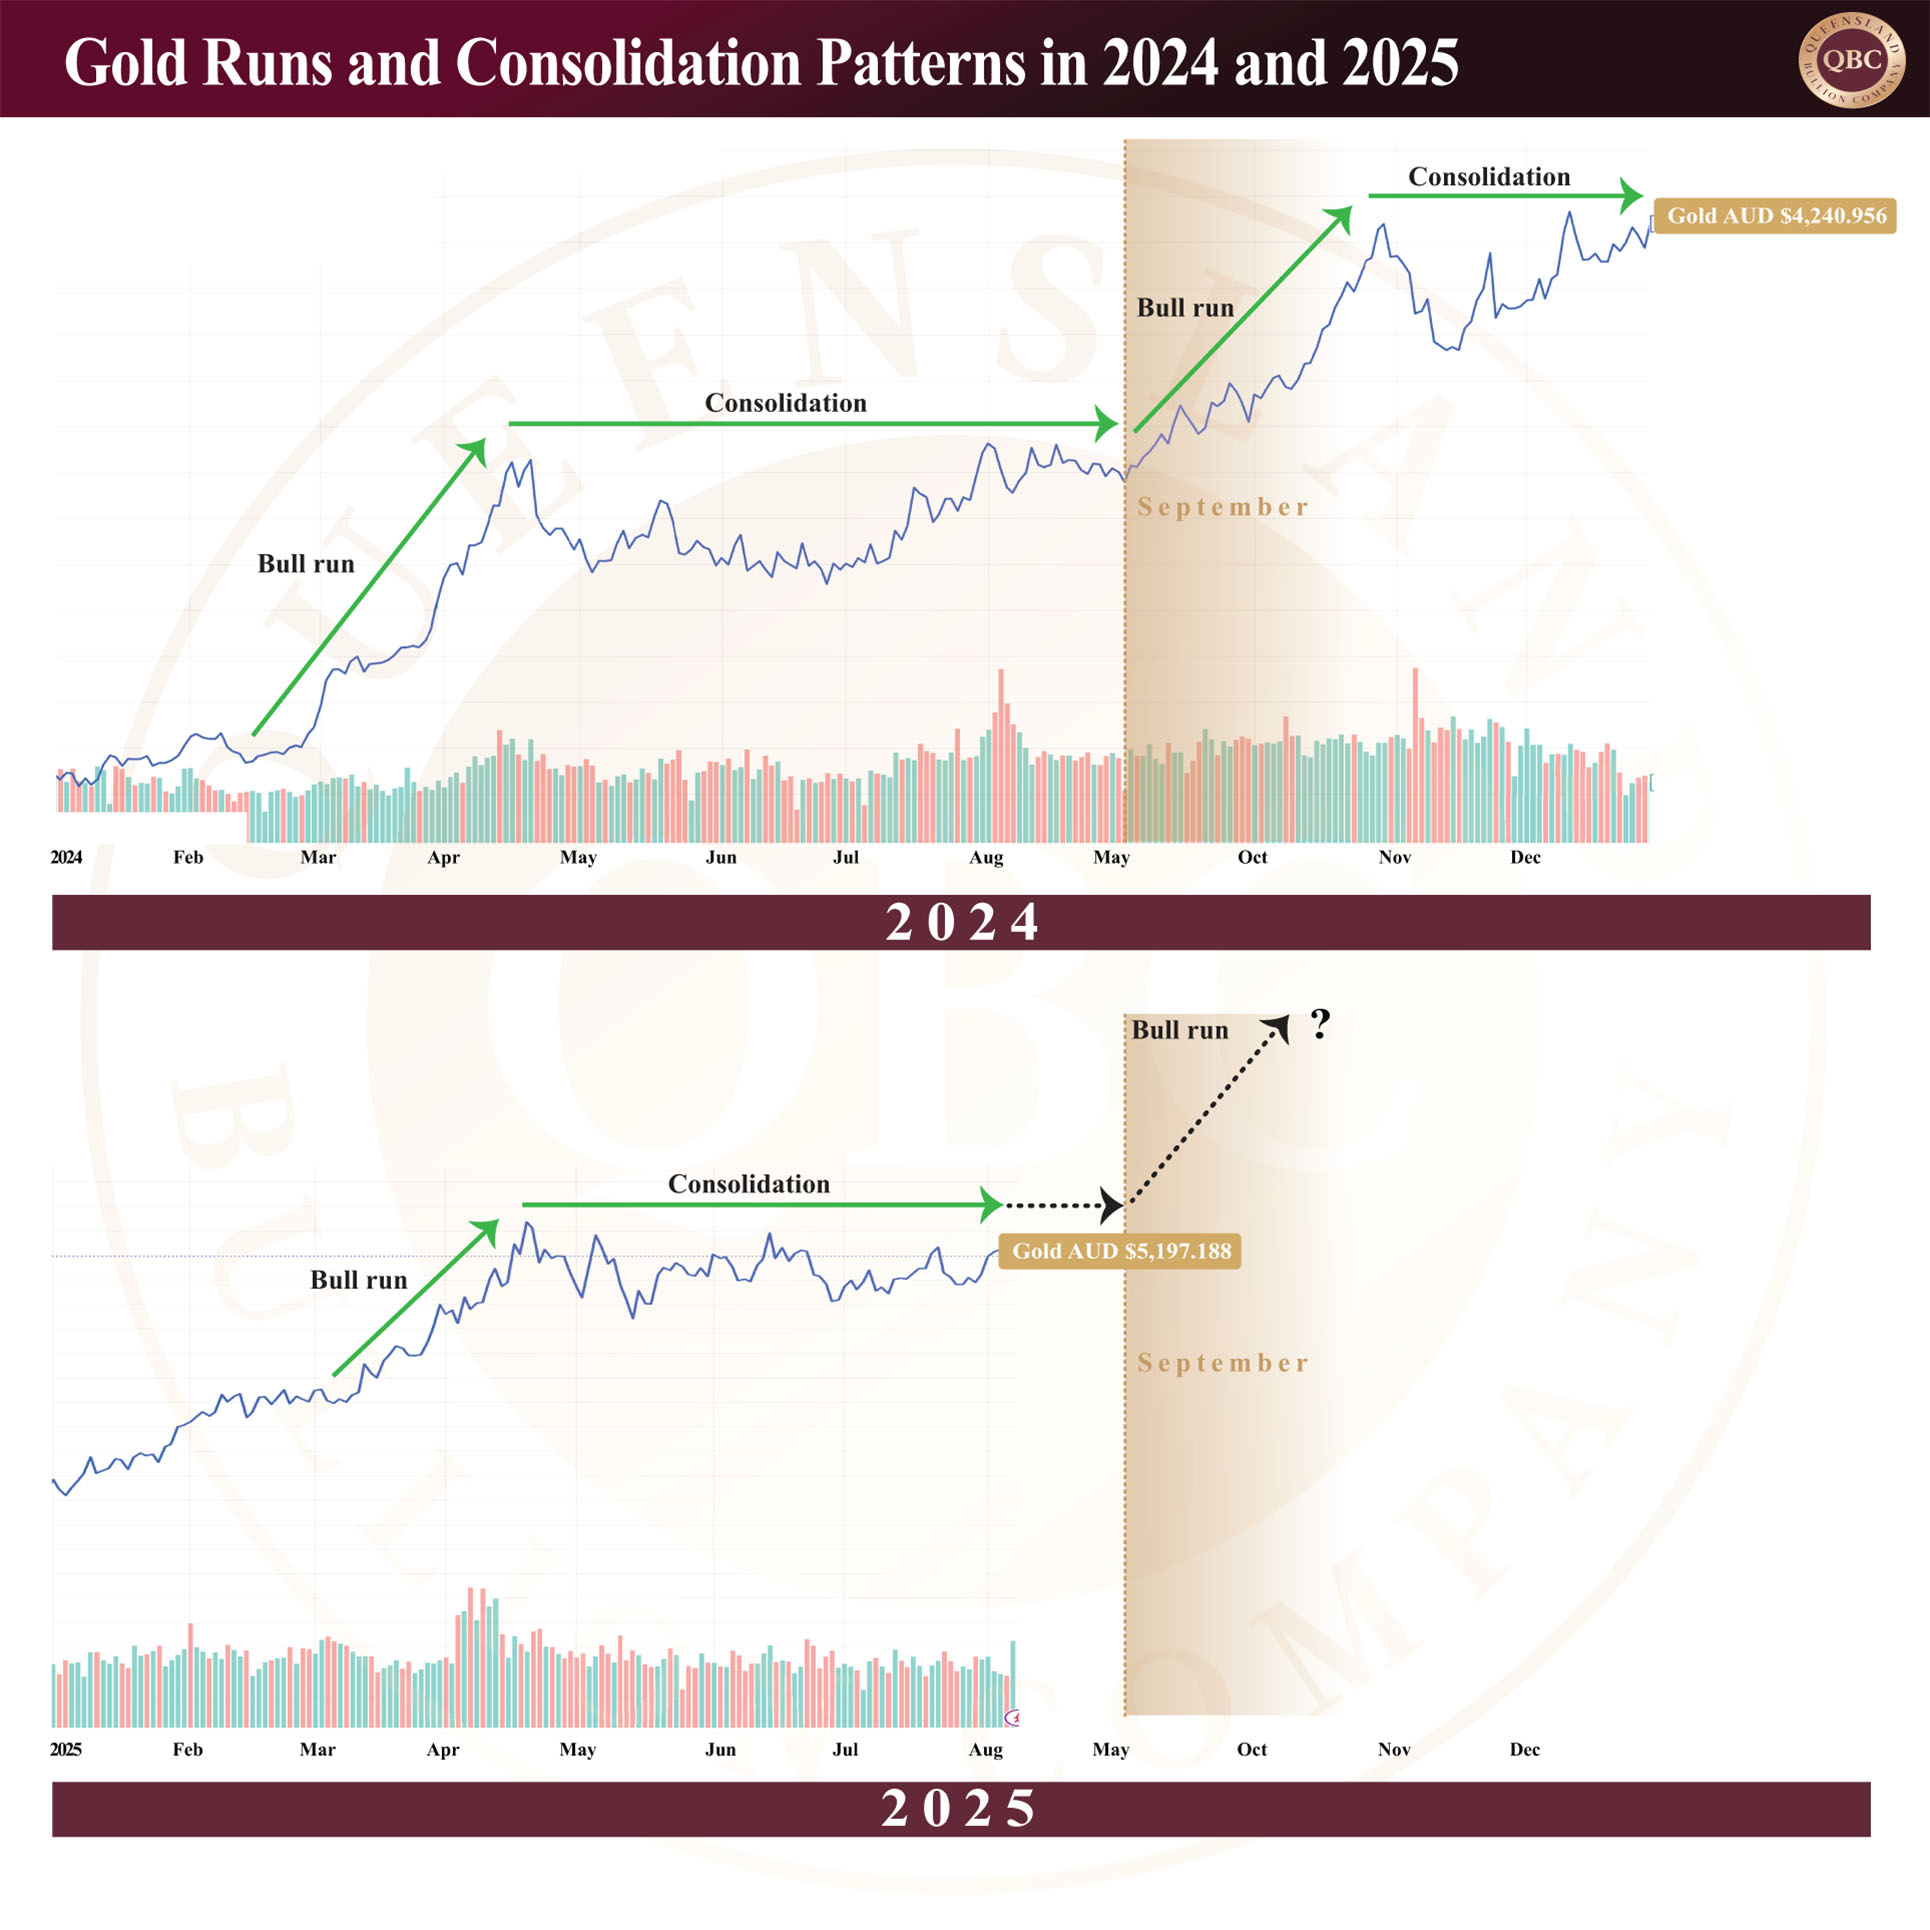
Today, gold and silver are again in focus but under different conditions. Gold in AUD terms has climbed over 400% since 2008, while silver is up over 280%. Technical data indicates a strong upward channel for gold, with repeated breakouts followed by consolidations, suggesting a healthy bull market rhythm. Furthermore, a comparison between 2024 and 2025 reveals striking symmetry, where both years saw explosive moves into April followed by mid-year consolidation, setting the stage for potential spring breakouts.  We first predicted this in May and the three months since has proven the theory to be true.

Silver’s technical analysis is also compelling. The recent push above AUD $58 comes after a bullish recovery from $56.18. Historical patterns show that silver tends to outperform gold in the final stages of a bull cycle. The gold-to-silver ratio, now around 1:88, remains far above historic norms such as 1:60 – 70, or the 2024 ratio of what is coming out of the ground at 1:15, implying further upside for silver if a true bull leg begins.


The Broader Market Context

Compared to the equity markets, gold and silver have offered resilience, but not the staggering gains of tech-heavy indices. The NASDAQ has risen over 1,173% since the 2008, while gold has increased 403% in AUD and 266% in USD. However, such growth in equities comes with significant risk, especially as the current cycle nears what the 18.6-year economic model identifies as the “Winner’s Curse” phase: the euphoric end of expansion before correction.  For example, the NASDAQ (tech stocks) has expanded almost six times faster than the M2 money supply (current cash available in America).  This indicates that the NASDAQ is probably at the top end of valuations.  Those invested in tech stocks may feel constrained if the financial corrections are quick and violent, whereas real estate investors are more likely to experience a slow burn as capitulation unfolds in stages over time.

With global debt at record levels and central banks approaching the end of their tightening cycles, conditions are ripe for a return to the monetary expansion playbook, one that historically favours precious metals. If rate cuts resume and inflation expectations rise, the setup may mirror the post-GFC years (early 2010s), where metals staged strong gains in response to policy shifts.


Final Thoughts

History does not repeat, but it often rhymes. During both the GFC and COVID, gold and silver offered protection. As we approach another inflection point, facing economic fragility, shifting rate expectations, and historically strong technical setups, precious metals may once again be poised to outperform.  With September approaching, which is traditionally viewed as crash season in the stock markets, the coming months may determine whether gold and silver are simply pausing… or preparing to leap.


Posted on — Leave a comment

Gold Coins or Gold Bars? Choosing the Right Gold Investment

For many Australians entering the world of precious metals investing, one of the first decisions to make is whether to buy gold coins or gold bars. Both options provide direct exposure to physical gold, but they serve slightly different purposes depending on your goals, budget, and storage preferences. Here’s how to assess which option makes the most sense for your portfolio.

Understanding the Basics

Gold coins and gold bars are both forms of investment-grade physical bullion. Coins, such as the Australian Kangaroo or the American Eagle, are minted by government entities and carry legal tender status. Bars, by contrast, are typically produced by private refineries with a focus on purity and value per gram.

Gold Coins: Liquid, Recognised and Flexible

Gold coins are often favoured by first-time investors thanks to their accessibility and flexibility. They provide easy liquidity and recognition when using widely traded coins like the South African Krugerrand or Canadian Maple Leaf and are recognised across global markets, making them easy to sell.  Gold coins are available in fractional sizes (e.g., 1/10oz, 1/4oz) which makes them ideal for investors building positions gradually.  They also have a potential for collectability, as certain coins can gain numismatic value over time due to limited mintage or historical relevance.  Finally, most coins come with a sovereign guarantee (government assurance) for weight and purity, all of which is essential to be a form of legal tender for the face value of the coin.

However, coins do tend to carry a higher premium over the spot price due to minting, design, and distribution costs. They also require more space and care in storage due to varied sizes and packaging.

Gold Cast Bars: Efficient for Larger Allocations

Gold cast bars are typically the preferred choice for those looking to allocate more capital into bullion.  Cast bars, even as small as half an ounce of gold (and especially at 1 kilogram), offer the best value per ounce when buying gold online.  Larger bars help reduce the average cost per ounce and consolidate wealth in fewer items.  The uniform sizing aids storage efficiency by making bars easier to stack and store in vaults or safes. In Australia investment-grade bars are at least 99.99% pure (or 99.95% pure for silver)  and come stamped with the purity, weight and brand.

Buying Gold Online: What to Know

Regardless of your preference, buying gold bullion online requires careful consideration:

  • Choose a reputable dealer with transparent pricing and a wide range of products.
  • Ensure secure delivery or storage options, such as insured vaulting. At Queensland Bullion Company, we offer secure storage options on the stunning Sunshine Coast that caters for both local and remote clients.
  • Understand return and authentication policies before you purchase.

Final Word

Whether you’re stacking sovereign gold coins or investing in larger bullion bars, owning physical metal is a proven way to hedge against uncertainty and preserve long-term purchasing power. The key is to match your bullion strategy with your investment objectives, and revisit it as your circumstances evolve.

At Queensland Bullion Company, we carry both gold coins and cast bars at the most up-to-date prices. If you would like to discuss your investment strategy with one of our sales executives feel welcome to book an appointment or call the office at any time.

Posted on — Leave a comment

Is Silver Undervalued?

Silver achieved a new all-time high when it reached AUD $59.91 last Monday, igniting hopes among investors for a climb to $2,000 per kilogram, or approximately $62.20 per ounce. The rally places silver, currently trading at $58.47, firmly back into the spotlight, joining gold ($5,088) and platinum ($2,201) as metals of increasing strategic interest. But is silver still undervalued at these levels? A deeper look into monetary supply, mining trends, market ratios, and chart patterns may suggest the answer is still yes.


M2 Money Supply  

One useful framework for evaluating silver’s worth is by comparing its price against the U.S. M2 money supply.  This indicator is the U.S. Federal Reserve’s estimate of liquid assets including cash, money in bank accounts and other deposits that can be readily convertible to cash.  This ratio reveals whether silver is keeping up with the expansion of fiat liquidity or falling behind.  If the value of an asset increases more quickly than the M2 money supply then it is more likely to experience a correction in price; conversely it is also true in that if the value of an asset lags behind the M2 money supply indicator then it will likely experience an increase at some point.  Since the mid-2010s, silver has lagged M2 growth, as it did before the Global Financial Crisis (GFC).  This is a potentially bullish signal for silver.

In short, while central banks have aggressively increased currency in circulation, the price of silver has not kept pace. If past patterns hold, the metal may be entering a prolonged phase of strength as it plays catch-up with inflationary expansion.


The Paper vs Physical Divide 

Few markets are as distorted as the silver market. The current ratio of 375 ounces of “paper” silver (via ETFs, futures, and other derivatives) to every 1 ounce of physical silver is staggering. Investment banks hold extensive short positions, many of them naked (meaning they’re not backed by actual metal).  These short positions give the appearance of there being much more silver in circulation than there really is.  As the market is flooded with silver paper contracts, it suppresses the price which leads to an undervaluation of the metal.

If silver prices continue rising, short sellers may be forced to close their positions en masse, triggering a short squeeze. For every $1 gain in silver, bullion banks collectively face losses exceeding $262 million. A $10 rally would create billions in losses — and panic buying to cover those shorts could push prices to extraordinary levels, particularly in the physical market where supply is tight.


Supply Deficits and Rising Demand

 Silver mining production in 2024 totalled just 25,000 metric tonnes, a figure dwarfed by rising demand in the industrial, solar, and investment sectors. According to The Silver Institute data, the market is on track for a fifth consecutive annual deficit in 2025.

This supply imbalance is unlikely to correct quickly. Much of the world’s silver is mined as a by-product of other metals like zinc or copper, limiting miners’ ability to increase output in response to silver-specific demand.  In developed countries mines take approximately five to ten years to wind up once a project is approved.  And it is likely that additional projects may not be considered until the price of silver increases.  Hence, the setup is clear: tightening supply, increasing use cases, and insufficient investment in new production capacity.


The Gold to Silver Ratio Speaks Volumes

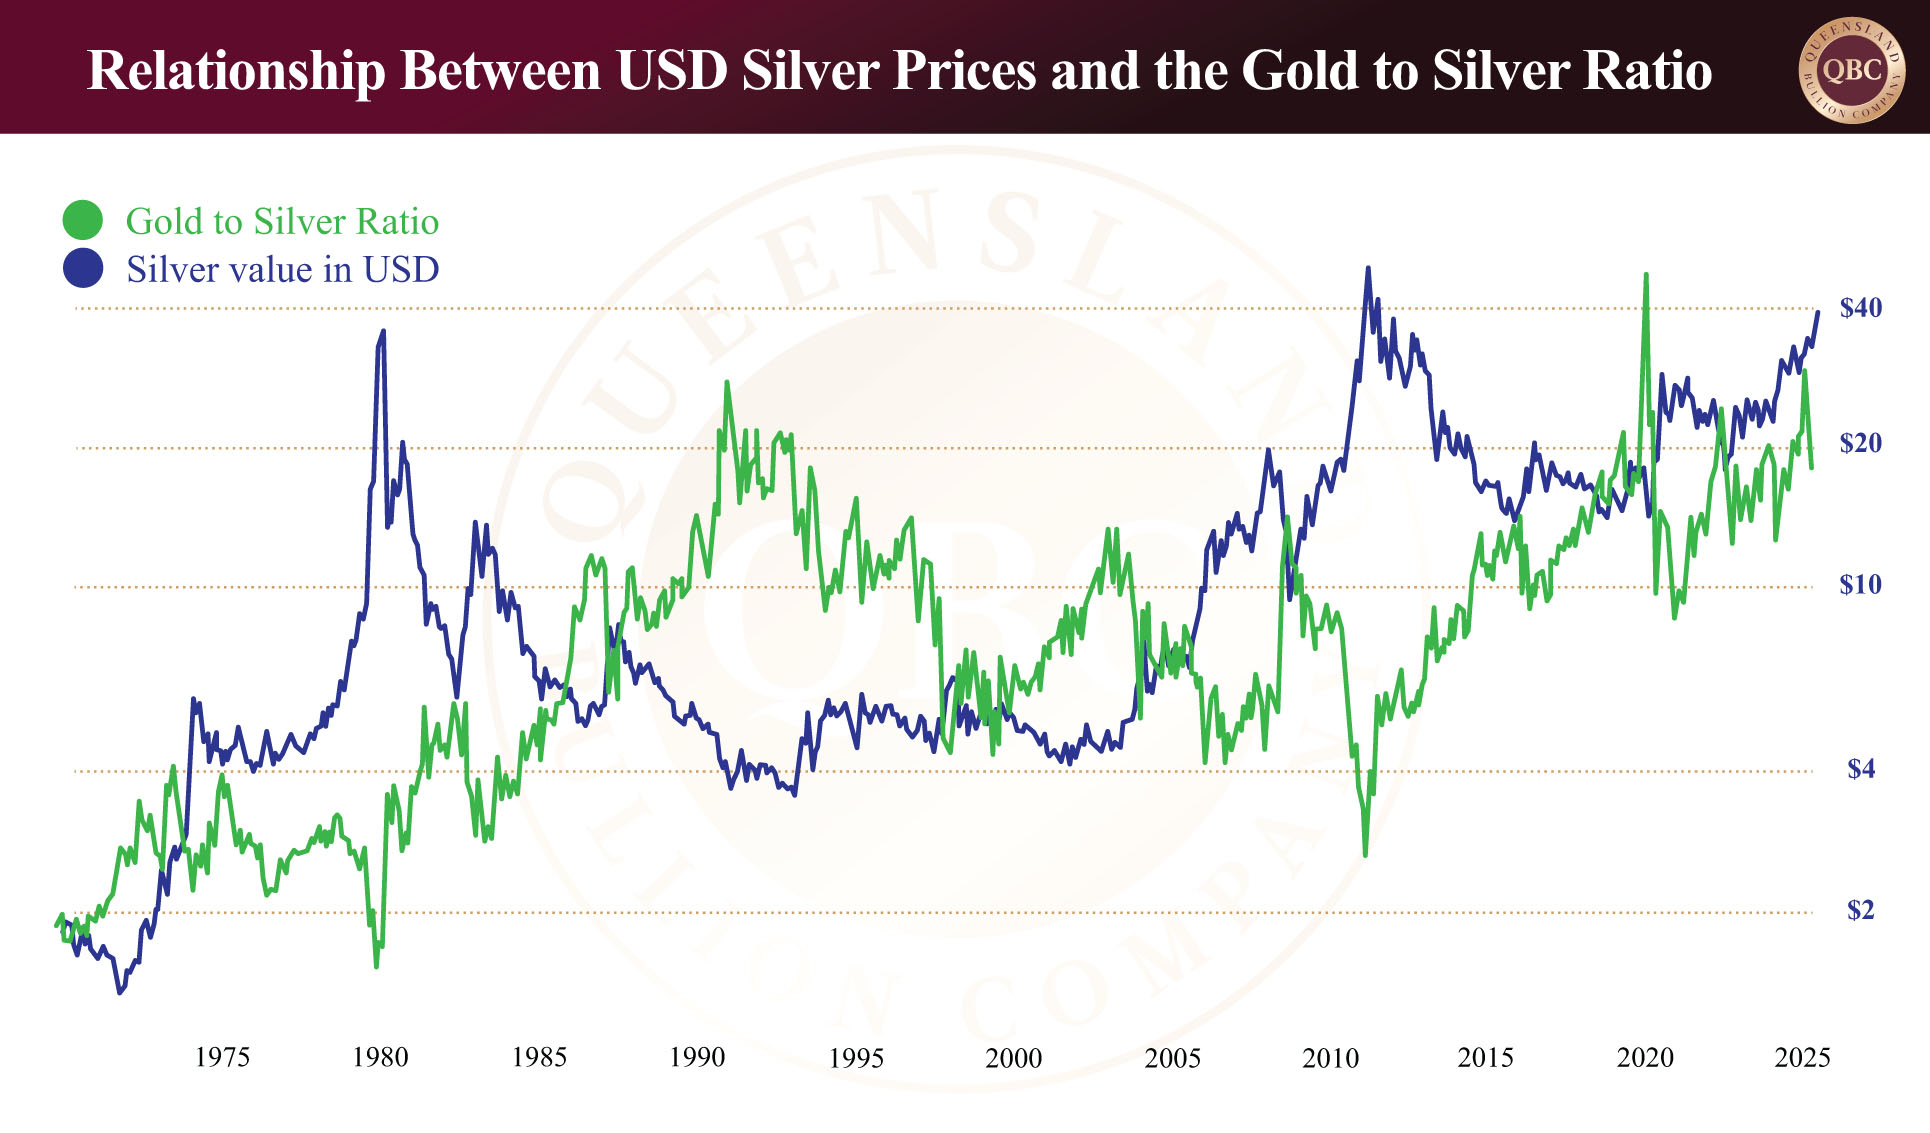
Perhaps one of the clearest signals of undervaluation is the gold-to-silver price ratio. Based on 2024 mining production quantities of gold and silver, for every one ounce of gold mined approximately 7.5 ounces of silver is produced. Yet the ratio is 1:86.31 at the time of writing.  This is still high compared to the historical average and suggests that the most recent increase in silver is likely at the very least sustainable, if not suggestive of further gains to come.

During historic silver bull markets, the ratio has narrowed significantly. April saw the ratio at 1:106; prior to the GFC it peaked at 1:104; and during the Covid 19 Pandemic Era it made history when it reached 1:124.   It dropped as low as 31.6 during the Global Financial Crisis in 2011 and dipped as low as 15.1 during the 1980s silver rush. Should silver return to even half of that historical compression, its upside potential becomes dramatic. What does this mean? The ratio simply reflects the relationship between gold and silver, in that if the price of silver increases faster than gold the ratio reduces.  If the price of gold increases faster than silver the ratio rises.  If they both rise or fall together the ratio generally reduces but at a slower rate.  For example, if the ratio is 1:80 would mean that for each $1 silver increases, gold would need to increase $80 to maintain the same ratio.


Charting the Future: The Cup and Handle 

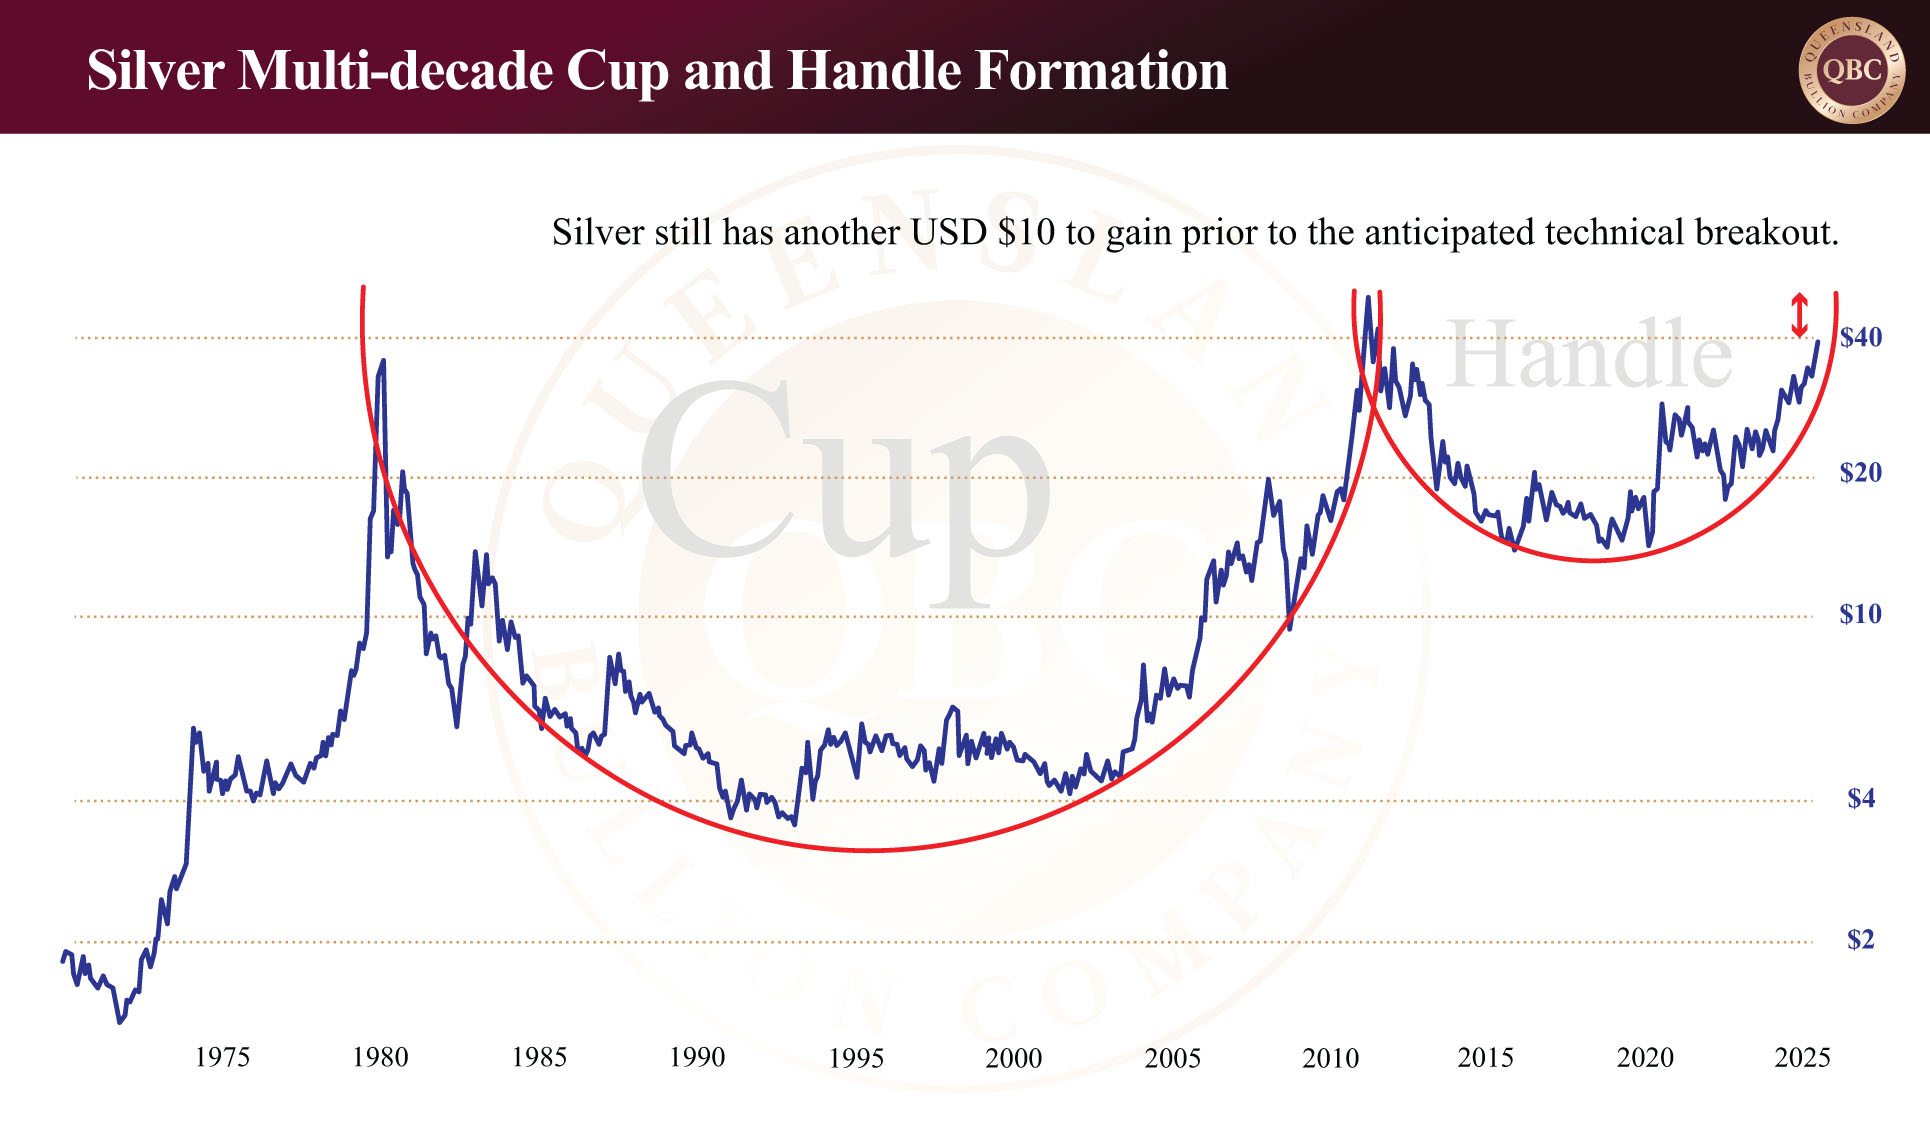
Technically, silver is nearing the final stages of a multi-decade cup and handle formation, one of the most powerful bullish setups in market history. Currently trading at USD $39.19, it is $10 short of its all-time high of $49.21 reached in 2011. Then silver hit the $40 threshold and1 it only took one month to breach $49. If the metal clears the psychological marker of $50, chartists anticipate a powerful breakout, potentially ushering in a fresh multi-year bull market with targets far above $60.  If silver plays catch up to gold, the gold to silver ratio will reduce as it did when it peaked in 1979 and 2011.  And this is when many silver bulls will look to take profits.


A Market Poised to Move

When measured against money supply, mining fundamentals, market ratios, and historical price action, silver still appears undervalued. A strong technical setup, combined with growing industrial demand and a fragile paper market, adds fuel to a potential surge.

For Australian investors, the implications are significant. As the USD-AUD exchange rate fluctuates and the global appetite for physical assets rises, silver remains a compelling candidate for strategic accumulation. Whether you prefer coins, bars, or both, the question may not be whether silver will rise, but when.  To read more on the timing of silver’s anticipated bull run read our previous article When Will the Silver Squeeze Begin?